











Best Mortgage Refinance Rates in California Compare Top Lenders

best mortgage refinance rates in California

COIN4U IN YOUR SOCIAL FEED

Finding the best mortgage refinance rates in California can save homeowners thousands of dollars over the life of their loan. With California’s competitive lending market and diverse economic landscape, securing favorable refinance terms requires understanding current market conditions, lender requirements, and timing strategies. Whether you’re looking to lower your monthly payments, access home equity, or switch from an adjustable to a fixed-rate mortgage, California offers numerous refinancing opportunities for qualified borrowers. This comprehensive guide explores today’s top refinance rates, qualification criteria, and expert strategies to help you secure the most competitive terms available in the Golden State.

Current Mortgage Refinance Landscape in California

California’s mortgage market remains one of the most dynamic in the nation, with rates fluctuating based on Federal Reserve policies, state economic conditions, and regional housing trends. The state’s high property values often mean larger loan amounts, which can work in borrowers’ favor when negotiating rates with lenders competing for substantial refinance business.

Major metropolitan areas like Los Angeles, San Francisco, and San Diego typically see the most competitive rates due to high loan volumes and intense lender competition. However, rural areas throughout California also benefit from state and federal programs designed to promote homeownership and refinancing accessibility.

Best Mortgage Refinance Rates in California

Traditional Banks and Credit Unions

Large national banks operating in California often offer competitive refinance rates, especially for existing customers. Wells Fargo, Bank of America, and JPMorgan Chase maintain significant California market share and frequently provide rate discounts for relationship banking customers.
best mortgage refinance rates in California

Credit unions throughout California typically offer some of the most attractive refinance terms. Navy Federal, Golden 1 Credit Union, and SchoolsFirst Federal Credit Union consistently rank among the top choices for California refinancing. These institutions often provide lower fees and more flexible qualification requirements than traditional banks.

Online Lenders and Mortgage Companies

Digital-first lenders have revolutionized California’s refinance market by offering streamlined applications and competitive rates. Companies like Quicken Loans, Better.com, and LenderFi provide entirely online experiences with often faster processing times than traditional lenders.

These platforms leverage technology to reduce operational costs, frequently passing savings to borrowers through lower rates or reduced closing costs. Many California homeowners appreciate the convenience and transparency these lenders provide throughout the refinance process.

Factors Affecting Your Refinance Rate in California

Credit Score Requirements

Your credit score significantly impacts the refinance rates available to you. Most California lenders require minimum scores of 620 for conventional refinancing, though the best rates typically go to borrowers with scores above 740. Even small credit score improvements can translate to substantial savings over your loan term.

Loan-to-Value Ratio Considerations

California’s high property values often result in favorable loan-to-value ratios for homeowners who have owned their properties for several years. Lenders prefer LTV ratios below 80% for the best rates, though many will refinance loans up to 95% LTV with appropriate pricing adjustments.

Employment and Income Verification

California’s diverse economy means lenders encounter various income types, from traditional W-2 employment to gig work and investment income. Documenting stable income remains crucial for securing favorable refinance terms, regardless of your employment structure.

Types of Refinance Options Available in California

Rate-and-Term Refinancing

This popular option allows California homeowners to secure better interest rates or change loan terms without increasing their loan balance. Many borrowers use rate-and-term refinancing to switch from 30-year to 15-year mortgages, building equity faster while securing lower rates.

Cash-Out Refinancing

California’s appreciation in home values makes cash-out refinancing attractive for homeowners needing funds for renovations, debt consolidation, or investment opportunities. This option allows borrowing against home equity while potentially securing better rates than your original mortgage.

Streamline Refinancing Programs

FHA and VA streamline programs offer simplified refinancing for qualified California borrowers. These programs often require minimal documentation and can provide faster processing times, making them popular choices for eligible homeowners.

Qualification Requirements for California Refinancing

Documentation Needed
Qualification Requirements for California Refinancing

California refinancing requires standard documentation, including recent pay stubs, tax returns, bank statements, and property information. Some lenders offer reduced documentation programs for borrowers with excellent credit and substantial equity.

Property Requirements

Your California property must meetthe  lender’s appraisal and condition standards. Most lenders require professional appraisals to determine current market value, though some offer automated valuation models for qualifying properties.

Debt-to-Income Ratios

California’s high cost of living means lenders often accept higher debt-to-income ratios than in other states. Most conventional loans allow DTI ratios up to 43%, while some government programs permit higher ratios with compensating factors.

Best Practices for Securing Low Refinance Rates

Shopping Multiple Lenders

California’s competitive lending environment makes rate shopping essential. Obtain quotes from at least three different lender types: traditional banks, credit unions, and online lenders. Compare not just rates but also fees, closing costs, and service quality.

Timing Your Application

Market timing can significantly impact your refinance rate. Monitor economic indicators and consider locking rates when favorable conditions emerge. California’s fast-paced real estate market means rates can change quickly.

Improving Your Financial Profile

Before applying, optimize your credit score, reduce debt balances, and gather complete documentation. Small improvements in your financial profile can qualify you for better rate tiers.

Common Refinancing Mistakes to Avoid

Focusing Only on Interest Rates

While securing low rates is important, California borrowers should also consider closing costs, loan terms, and lender reputation. Sometimes, slightly higher rates with lower fees provide better overall value.

Not Considering Break-Even Analysis

Calculate how long you’ll need to remain in your California home to recoup refinancing costs through lower payments. This analysis helps determine whether refinancing makes financial sense for your situation.

State-Specific Programs and Incentives

California offers several refinancing assistance programs for qualified homeowners. The California Housing Finance Agency provides various refinancing options, particularly for moderate-income borrowers and first-time homebuyers who previously used state programs.

Additionally, some California municipalities offer local refinancing assistance programs, particularly in areas focused on affordable housing preservation and community development.

Working with California Mortgage Professionals

Choosing the Right Loan Officer

Select experienced loan officers familiar with California’s unique market conditions and regulatory environment. Local expertise can prove valuable in navigating state-specific requirements and identifying the best program options.

Understanding Closing Processes

California’s closing processes can vary by region, with different requirements in Northern and Southern California. Work with professionals who understand local procedures and can ensure smooth transaction completion.

Conclusion

Securing the best mortgage refinance rates in California requires research, preparation, and strategic timing. By understanding current market conditions, comparing multiple lenders, and optimizing your financial profile, you can access the competitive rates that California’s diverse lending market offers. Whether you’re looking to reduce monthly payments, access home equity, or improve loan terms, now is an excellent time to explore your refinancing options. Start by requesting rate quotes from at least three different lenders and consider working with experienced California mortgage professionals who can guide you through the process and help you secure the best possible terms for your unique situation.

Explore more articles like this

Subscribe to the Finance Redefined newsletter

A weekly toolkit that breaks down the latest DeFi developments, offers sharp analysis, and uncovers new financial opportunities to help you make smart decisions with confidence. Delivered every Friday

By subscribing, you agree to our Terms of Services and Privacy Policy

READ MORE

Cryptocurrency and Digital Commerce Regulation Guide

Cryptocurrency and Digital

COIN4U IN YOUR SOCIAL FEED

The rapid rise of cryptocurrency and the expansion of digital commerce have reshaped modern finance, online business models and global economic behaviour. What began as a technological experiment driven by decentralised digital currencies has evolved into a sophisticated ecosystem that includes blockchain networks, tokenised assets, decentralised finance and innovative digital payment solutions. As more consumers and businesses adopt these technologies, the need for strong and balanced cryptocurrency and digital commerce regulation becomes increasingly essential. Regulation must address transparency, safety, consumer protection and financial stability without hindering the innovation that fuels economic progress.

The regulatory environment around cryptocurrency and digital commerce is complex because it must align with rapidly evolving technologies. Governments across the world are trying to create frameworks that ensure security and accountability while supporting growth in financial and technological sectors. Businesses involved in digital trade must understand how regulations apply to them, and users must be aware of how these rules protect their rights and assets. This article explores the full landscape of cryptocurrency and digital commerce regulation, providing clarity on why regulation matters, how laws differ across regions and what the future of the digital economy might look like.

Cryptocurrency and Digital Commerce

To understand the purpose and structure of cryptocurrency and digital commerce regulation, it is important to first define the digital components at the heart of this transformation. Cryptocurrency refers to digital assets secured by cryptographic algorithms and powered by distributed ledger technology. These assets operate on blockchain networks, where transactions are recorded transparently and immutably. Bitcoin and Ethereum are the two most widely recognised cryptocurrencies, but thousands of tokens exist today, each serving different functions in digital ecosystems. Unlike traditional currencies, cryptocurrencies operate without a central authority, allowing fast, borderless and peer-to-peer transactions that bypass traditional banking systems.

Digital commerce refers to the buying and selling of goods and services using electronic platforms, ranging from online stores and mobile apps to digital marketplaces and subscription platforms. With the integration of cryptocurrencies into mainstream commerce, digital commerce has expanded into a broader digital economy. Users can purchase goods, access digital services or invest in tokenised assets directly from their digital wallets. This integration, while beneficial, introduces new regulatory challenges, especially in areas such as consumer rights, taxation, transaction transparency and platform accountability.

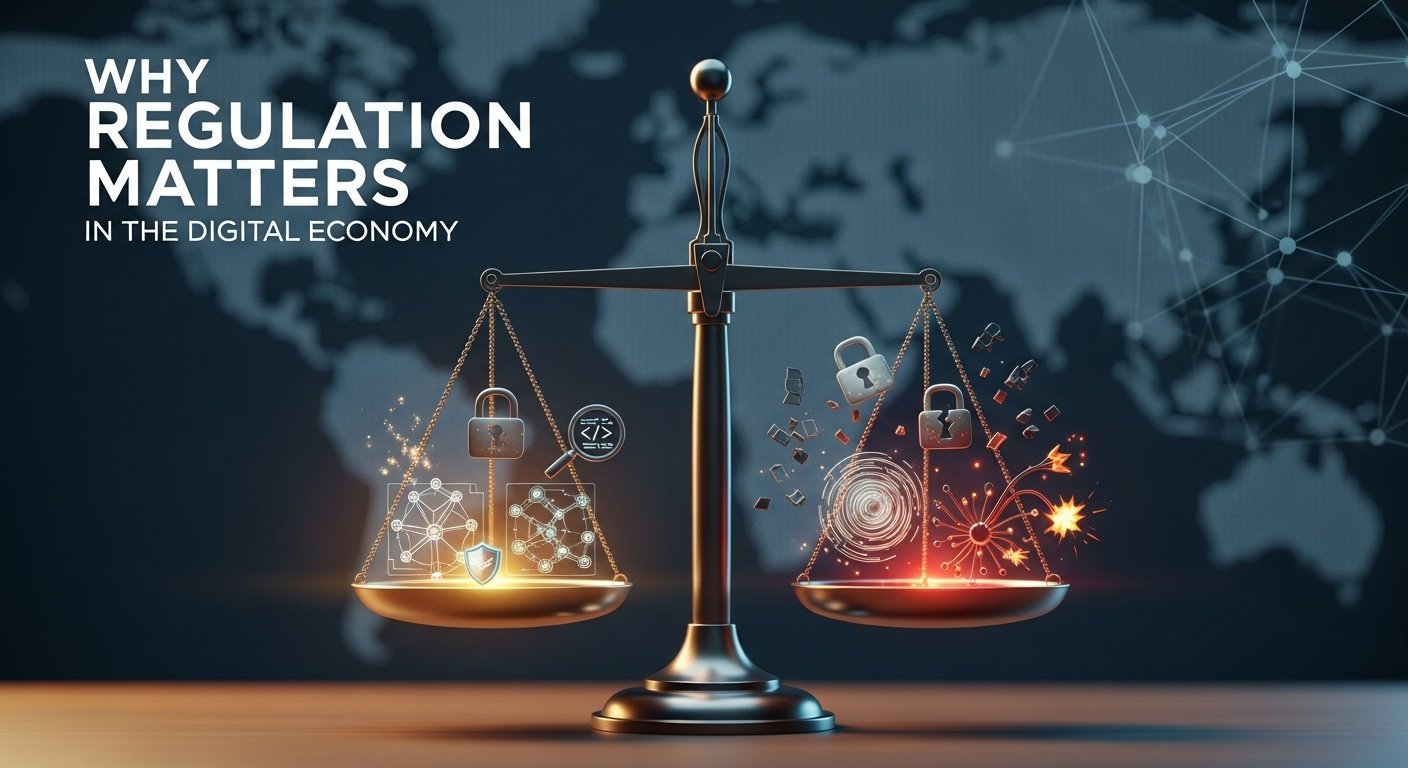
Why Regulation Matters in the Digital Economy

Why Regulation Matters in the Digital Economy

Regulation in the cryptocurrency and digital commerce space is necessary to ensure stability, prevent abuse and promote trust. Consumers engaging with cryptocurrencies often lack deep technical which can expose them to risks such as price volatility, phishing attacks, wallet compromises and fraudulent platforms. Without regulatory protection, users may suffer irreversible losses. Consumer protection laws adapted to digital technology ensure that businesses offering crypto services maintain transparent policies, secure infrastructure and fair dispute mechanisms.

Another major reason regulation is important is the need to combat financial crime. Cryptocurrencies have occasionally been misused for illegal activities because transactions can be pseudonymous and instantaneous. Regulators implement anti-money laundering controls and require service providers to verify user identities to reduce the potential for illicit activity. These rules allow law enforcement and financial authorities to detect suspicious behaviour while enabling legitimate transactions to flourish. By enforcing compliance, governments prevent crypto from becoming a haven for criminal enterprises.

Regulation also ensures fairness across the financial industry. Traditional finance institutions must comply with extensive legal requirements, while early crypto platforms once operated without comparable oversight. Creating a level regulatory framework ensures healthy competition while preventing new companies from gaining unfair advantages through regulatory gaps. In the long run, well-crafted regulations support innovation by creating clear rules, encouraging responsible growth and building confidence among investors, consumers and businesses.

Key Pillars of Cryptocurrency and Digital Commerce Regulation

Regulatory systems around the world generally focus on a few major themes, despite differences in legal traditions and economic priorities. One of the most important themes involves the classification of digital assets. Depending on their design and purpose, cryptocurrencies may be treated as currencies, commodities, securities or utility tokens. This classification determines which laws apply to the asset and how businesses must handle it. For example, a token that resembles an investment contract may be subject to securities regulation, requiring detailed disclosures and investor protections.

Another key pillar involves licensing and registration for crypto-related service providers. Exchanges, custodial wallet providers, payment processors and platforms offering token investment opportunities often need official authorisation to operate. Regulators require these businesses to maintain proper financial records, secure customer assets and demonstrate that they can operate safely. Licensing ensures that service providers meet minimum standards, reducing the risk of fraud or mismanagement.

Compliance with anti-money laundering and know-your-customer laws is another foundational aspect of cryptocurrency and digital commerce regulation. Businesses handling digital assets must verify customer identities, monitor unusual activities and report suspicious transactions to financial authorities. These procedures discourage criminal misuse of cryptocurrency and help integrate digital assets into the global financial system. Users may find identity verification burdensome, but it is essential for maintaining the integrity of the digital economy.

Taxation is another major element of regulation. Governments must determine how to tax crypto transactions, whether treating gains as capital income, business income or property-based gains. Merchants accepting cryptocurrency may need to convert values for tax reporting at the moment of the transaction. Staking rewards, mining profits and NFT sales may also carry tax obligations. Regulations help both individuals and businesses understand their responsibilities and avoid accidental non-compliance.

Finally, consumer rights and data protection form a growing area of digital commerce regulation. With users sharing personal information online and transacting digitally, rules surrounding privacy, cybersecurity, refund policies, and platform transparency are becoming increasingly important. Regulators expect businesses to secure sensitive information, communicate risks clearly and respond efficiently in case of breaches or service failures.

How Different Regions Approach Crypto and Digital Commerce

How Different Regions Approach Crypto and Digital Commerce

Regulatory approaches differ significantly across regions, reflecting varying attitudes toward innovation, financial stability and consumer protection. In North America, the regulatory environment is fragmented, especially in the United States, where different federal agencies interpret cryptocurrencies differently. Some agencies classify certain tokens as commodities while others treat them as securities. States may also impose individual licensing requirements, creating a multi-layered regulatory landscape. Canada has established a more streamlined system that treats many crypto trading platforms as securities dealers, requiring them to follow strict investor protection rules. Both countries pay close attention to issues related to stablecoins, decentralised platforms and tokenised securities.

Europe has moved toward a harmonised regulatory structure with the introduction of the Markets in Crypto-Assets framework. This regulation provides detailed rules for crypto asset service providers across the European Union, focusing on transparency, consumer protection and market integrity. Europe also applies strong privacy and e-commerce standards, which means crypto platforms must comply with multiple layers of regulation. As a region, the European Union leans toward treating digital assets similarly to traditional financial instruments while also supporting responsible innovation.

In the Asia-Pacific region, regulatory attitudes vary widely. Some countries promote technology development and crypto adoption by creating clear licensing regimes and innovation-friendly laws. Others impose strict limits on cryptocurrency trading or ban certain activities altogether. The region is diverse, but there is a common focus on controlling capital flows and ensuring financial stability. Many governments in the region pay special attention to cross-border payments, digital entertainment markets, gaming platforms and remittance services powered by blockchain.

Regulation of Crypto Payments in Digital Commerce

The use of cryptocurrency for everyday transactions has grown steadily, with more merchants accepting digital assets as payment for goods and services. Regulation plays a critical role in this area because both consumers and merchants need clarity on legal, tax and security aspects of crypto transactions. When a merchant receives cryptocurrency directly, they must understand how local laws treat digital assets, whether they must convert payments into fiat currency, and how to compute taxable income. Because crypto transactions are irreversible, consumer refund rights and chargeback policies must also be clearly defined.

Payment gateways that convert cryptocurrency to fiat currency offer additional convenience but also take on regulatory responsibilities. These companies often act as intermediaries and may need to comply with financial licensing rules, maintain secure processing systems and protect customer information. Their role makes cryptocurrency payments more accessible to merchants who prefer not to manage blockchain wallets themselves.

Stablecoins have become especially important in digital commerce because they offer the benefits of blockchain transactions without the extreme price volatility associated with many cryptocurrencies. However, stablecoins raise regulatory questions about issuer responsibility, reserve backing and systemic risk. Governments aim to ensure that stablecoin issuers hold sufficient assets to support redemption and operate with full transparency. As stablecoins become more integrated into digital commerce, they are likely to face increasingly detailed regulatory oversight.

See More: Comprehensive Guide to Cryptocurrency Blockchain and Digital Finance

Compliance Challenges for Businesses

Businesses operating in cryptocurrency and digital commerce face unique challenges because regulations evolve rapidly and differ across countries. One of the biggest challenges involves managing obligations across multiple jurisdictions. Since digital platforms typically serve global audiences, businesses may need to comply with several regulatory frameworks simultaneously. Some companies choose to limit services in certain regions to avoid legal complexity, while others invest heavily in compliance infrastructure to operate globally.

A second major challenge is balancing user privacy with regulatory oversight. Cryptocurrency users often prefer anonymity or pseudonymity, yet regulators require transparency for the sake of financial security and anti-crime measures. Businesses must find ways to respect user privacy while implementing identity verification and monitoring systems. Emerging technologies such as zero-knowledge proofs may eventually help reconcile privacy goals with regulatory requirements, but regulators are still learning how to apply these tools.

Cybersecurity presents another significant challenge. Digital assets are vulnerable to hacking, phishing attacks and technical failures. Businesses must implement strong security systems, conduct frequent audits and prepare detailed response plans for security incidents. Operational resilience is increasingly becoming a regulatory expectation, and companies that fail to secure customer assets may face penalties, reputational damage and loss of trust.

Future Trends in Cryptocurrency and Digital Commerce Regulation

The future of cryptocurrency and digital commerce regulation will likely involve greater integration between digital and traditional finance. As banks, fintech companies and established financial institutions adopt blockchain technology, regulatory frameworks may become more unified. Tokenisedd securities, digital bonds and central bank digital currencies are examples of products that will blur the line between decentralised and centralised finance. This convergence may lead to clearer rules and more predictable compliance expectations.

International cooperation is another emerging trend. Because blockchain networks operate globally, no single nation can regulate digital assets effectively on its own. International organisations and regulatory bodies are working toward consistent global standards on issues such as anti-money laundering, cross-border taxation and supervision of virtual asset service providers. More coordinated regulation can reduce fragmentation and help businesses operate more confidently across multiple markets.

Finally, regulation is becoming more technologically informed. Policymakers are increasingly willing to learn about blockchain mechanisms, smart contract design and decentralised architectures instead of applying outdated laws rigidly. This shift can encourage innovation by allowing regulators to craft rules that address outcomes rather than specific technologies. Regulatory sandboxes, pilot programs and public consultations will likely become more common as authorities seek to understand how emerging technologies can coexist with financial safeguards.

Conclusion

Cryptocurrency and digital commerce are transforming the global economy by enabling faster, more secure and more transparent ways of transferring value. As adoption grows, the importance of strong, clear and flexible cryptocurrency and digital commerce regulation becomes undeniable. Regulation protects consumers, prevents financial crime, maintains market integrity and creates a stable environment for innovation. While regulatory approaches differ across regions, the trend is toward more structured and cooperative frameworks that integrate digital assets into mainstream finance.

Users benefit when they understand how regulations affect their rights, security and responsibilities. Businesses succeed when they embrace compliance as part of their long-term strategy and design their platforms with regulatory expectations in mind. As the digital economy evolves, those who recognise regulation as. Pillar of trust—not a barrier—will be best positioned to thrive in the future of digital finance.

Explore more articles like this

Subscribe to the Finance Redefined newsletter

A weekly toolkit that breaks down the latest DeFi developments, offers sharp analysis, and uncovers new financial opportunities to help you make smart decisions with confidence. Delivered every Friday

By subscribing, you agree to our Terms of Services and Privacy Policy

READ MORE

ADD PLACEHOLDER