



































The global financial ecosystem is undergoing a profound transformation as blockchain technology continues to reshape traditional systems. From decentralized finance to tokenized assets, innovation is accelerating at an unprecedented pace. One of the most significant developments in this evolving landscape is the emergence of blockchain-based bonds, a financial instrument that merges the reliability of traditional debt markets with the efficiency of distributed ledger technology. Recently, a groundbreaking milestone has been achieved with Ripple Custody securing South Korea’s first insurance deal for blockchain bonds, marking a pivotal moment for both digital asset custody and institutional adoption.
This development is more than just another headline in the crypto industry. It represents a major step toward addressing one of the biggest concerns surrounding blockchain finance: security and trust. By integrating insurance into blockchain bond infrastructure, Ripple Custody is helping bridge the gap between traditional financial institutions and the rapidly evolving world of tokenized securities. South Korea, known for its advanced technological ecosystem and proactive regulatory stance, is emerging as a key player in this transformation.
In this article, we explore the significance of Ripple Custody’s insurance deal, its implications for blockchain bonds, and how it could reshape the future of global finance. We will also examine the broader impact on institutional crypto adoption, regulatory frameworks, and investor confidence.
The Rise of Blockchain Bonds in Modern Finance
Understanding Blockchain Bonds
Blockchain bonds are essentially digital representations of traditional bonds issued and managed using distributed ledger technology. Unlike conventional bonds, which rely on centralized intermediaries, blockchain bonds operate on decentralized networks, offering greater transparency, efficiency, and security. This innovation allows issuers to streamline processes such as issuance, settlement, and compliance.
The integration of smart contracts further enhances the functionality of blockchain bonds. These automated agreements execute predefined conditions without the need for manual intervention, reducing operational costs and minimizing human error. As a result, blockchain bonds are gaining traction among financial institutions seeking to modernize their infrastructure.
Why Institutions Are Turning to Tokenized Debt
The growing interest in blockchain bonds is driven by several factors. First, the efficiency gains associated with blockchain technology significantly reduce settlement times, which traditionally take days. Second, the transparency of distributed ledgers ensures that all transactions are verifiable and immutable, enhancing trust among participants.
Moreover, tokenization enables fractional ownership, allowing a broader range of investors to participate in debt markets. This democratization of finance is particularly appealing in emerging markets where access to traditional financial instruments may be limited. As a result, tokenized assets are becoming a cornerstone of the next-generation financial system.
Ripple Custody’s Role in the Digital Asset Ecosystem
What Is Ripple Custody?
Ripple Custody is a specialized solution designed to provide secure storage and management of digital assets. As institutional interest in cryptocurrencies and blockchain-based instruments grows, the need for robust custody solutions has become increasingly critical. Ripple Custody addresses this demand by offering enterprise-grade security, compliance tools, and seamless integration with existing financial systems.
The platform leverages advanced encryption techniques and multi-layered security protocols to safeguard assets. This ensures that institutions can confidently engage with blockchain-based financial products without exposing themselves to undue risk.
Bridging Traditional Finance and Blockchain
One of Ripple Custody’s primary objectives is to bridge the gap between traditional finance and the blockchain ecosystem. By providing a secure and compliant infrastructure, it enables banks, asset managers, and other institutions to explore new opportunities in digital finance.
The recent insurance deal in South Korea is a testament to this mission. By incorporating insurance into its custody services, Ripple Custody is addressing a critical barrier to adoption: the lack of risk mitigation mechanisms. This move not only enhances security but also aligns blockchain-based products with traditional financial standards.
South Korea’s Strategic Position in Blockchain Innovation
A Tech-Forward Financial Hub
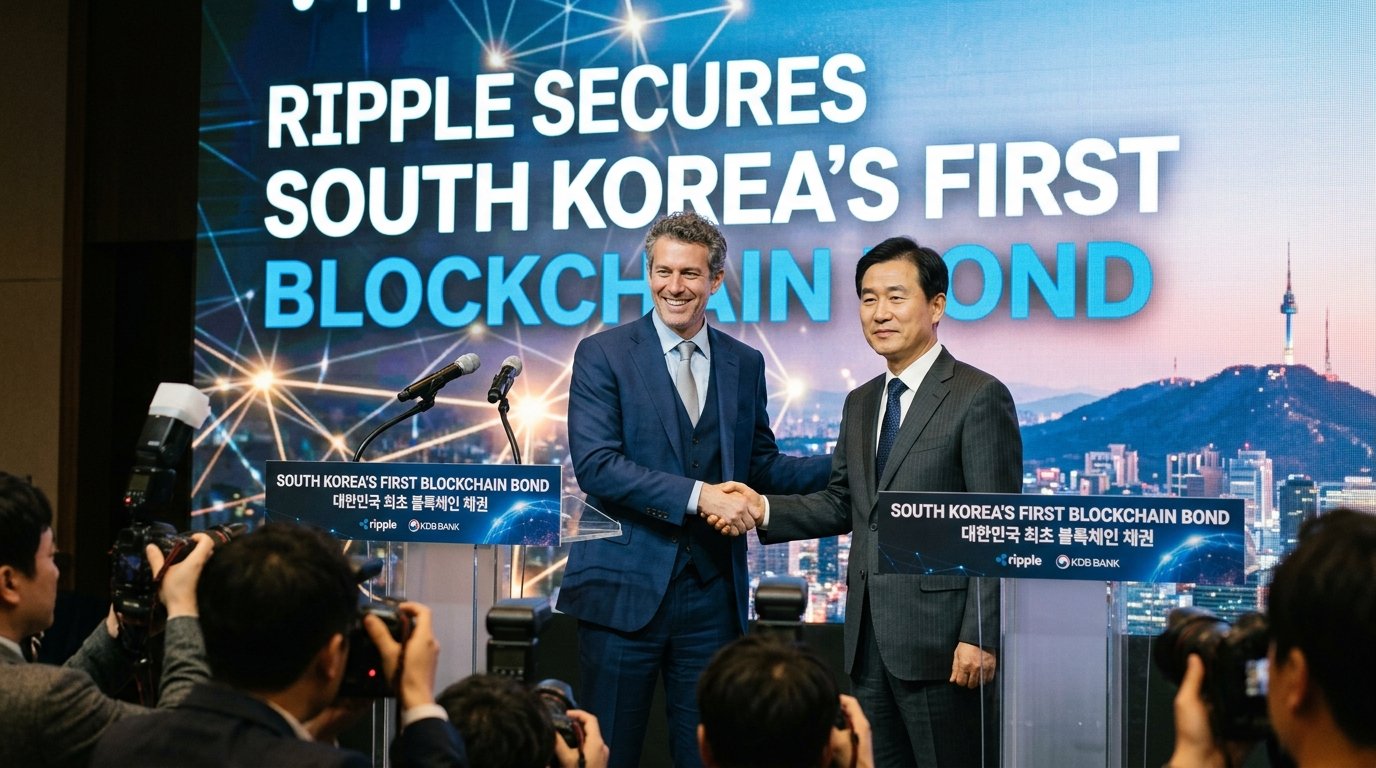
South Korea has long been recognized as a leader in technological innovation. With a highly developed digital infrastructure and a tech-savvy population, the country is well-positioned to embrace blockchain technology. The government has also taken proactive steps to regulate the crypto industry, creating a balanced environment that encourages innovation while ensuring investor protection.
This forward-thinking approach has made South Korea a fertile ground for developments such as blockchain bonds and crypto custody solutions. The Ripple Custody insurance deal is a natural progression in this ecosystem, reflecting the country’s commitment to advancing digital finance.
Regulatory Support and Market Confidence
Regulation plays a crucial role in the adoption of blockchain-based financial instruments. In South Korea, regulators have been working to establish clear guidelines for digital assets, fostering a sense of stability and trust. This has encouraged both domestic and international players to invest in the market.
The introduction of insurance for blockchain bonds further strengthens this confidence. By providing an additional layer of protection, it reassures investors and institutions that their assets paving the way for broader adoption.
The Significance of the Insurance Deal
Enhancing Security and Risk Management
The integration of insurance into blockchain bond infrastructure represents a major advancement in risk management. Traditionally, digital assets have been perceived as high-risk due to concerns about hacking, fraud, and operational vulnerabilities. By offering insurance coverage, Ripple Custody is mitigating these risks and making blockchain bonds more appealing to institutional investors.
This development also aligns with the practices of traditional finance, where insurance plays a critical role in safeguarding assets. By adopting similar mechanisms, blockchain-based products are becoming more compatible with existing financial systems.
Building Institutional Trust
Trust is a fundamental component of any financial system. Without it, adoption remains limited. The Ripple Custody insurance deal addresses this challenge by providing a tangible assurance of security. This is particularly important for institutions, which are often bound by strict risk management policies.
As trust increases, so does participation. The introduction of insured blockchain bonds is likely to attract a wider range of investors, including pension funds, insurance companies, and sovereign wealth funds. This influx of capital could significantly accelerate the growth of the blockchain finance ecosystem.
Impact on Institutional Crypto Adoption
Lowering Barriers to Entry
One of the biggest obstacles to institutional adoption of cryptocurrencies and blockchain-based assets has been the lack of secure infrastructure. By combining custody services with insurance, Ripple Custody is effectively lowering these barriers.
Institutions that were previously hesitant to enter the market may now feel more comfortable doing so. This could lead to a surge in demand for digital asset investment products, further driving innovation and market growth.
Expanding the Use Cases of Blockchain
The success of this insurance deal could also pave the way for new applications of blockchain technology. Beyond bonds, other financial instruments such as equities, derivatives, and real estate assets could be tokenized and insured.
This expansion would not only diversify the blockchain ecosystem but also enhance its utility in real-world applications. As more use cases emerge, the technology’s value proposition becomes increasingly compelling.
Challenges and Considerations
Regulatory Complexity
While the Ripple Custody insurance deal is a significant milestone, it also highlights the complexity of regulating blockchain-based financial products. Different jurisdictions have varying approaches to digital assets, creating challenges for global adoption.
Ensuring compliance with local regulations while maintaining interoperability across markets will be a key challenge for industry players. However, initiatives like this insurance deal demonstrate that progress is being made.
Technological Risks
Despite advancements in security, blockchain technology is not immune to risks. Issues such as smart contract vulnerabilities and network attacks remain concerns. Continuous innovation and rigorous testing will be essential to address these challenges.
The inclusion of insurance provides a safety net, but it should not be seen as a substitute for robust security measures. Instead, it should complement ongoing efforts to enhance the resilience of blockchain systems.
The Future of Blockchain Bonds and Custody Solutions
A New Era of Financial Innovation
The Ripple Custody insurance deal marks the beginning of a new era in financial innovation. As blockchain technology continues to evolve, we can expect to see such initiatives that bridge the gap between traditional and digital finance.
Blockchain bonds are likely to become a mainstream financial instrument, offering a more efficient and transparent alternative to traditional debt markets. With the added layer of insurance, their appeal to institutional investors will only grow.
Global Implications
While this development is centered in South Korea, its impact is likely to be felt globally. Other countries may follow suit, adopting similar models to enhance their financial ecosystems. This could lead to the standardization of insured blockchain-based financial products, further accelerating adoption.
As the industry matures, collaboration between technology providers, financial institutions, and regulators will be crucial. Together, they can create a robust and sustainable framework for the future of finance.
Conclusion
The announcement that Ripple Custody has secured South Korea’s first insurance deal for blockchain bonds is a landmark achievement in the evolution of digital finance. By addressing key concerns حول security and trust, this initiative is paving the way for broader institutional adoption of blockchain-based financial instruments.
The integration of insurance into blockchain bond infrastructure not only enhances risk management but also aligns these innovative products with traditional financial standards. As a result, investors and institutions can engage with greater confidence, driving growth and innovation in the sector.
Looking ahead, the implications of this development extend far beyond South Korea. It sets a precedent for other markets and highlights the potential of insured digital assets to transform the global financial landscape. As blockchain technology continues to mature, initiatives like this will play a crucial role in shaping the future of finance.
FAQs
Q. What are blockchain bonds?
Blockchain bonds are digital versions of traditional bonds issued and managed using distributed ledger technology, offering greater transparency and efficiency.
Q. Why is insurance important for blockchain bonds?
Insurance provides an additional layer of security, protecting investors against risks such as hacking or operational failures, thereby increasing trust.
Q. How does Ripple Custody enhance digital asset security?
Ripple Custody uses advanced encryption, multi-layered security protocols, and compliance tools to safeguard digital assets for institutional investors.
Q. Why is South Korea significant in this development?
South Korea’s advanced tech infrastructure and supportive regulatory environment make it a leading hub for blockchain innovation.
Q. What does this mean for the future of finance?
This development signals increased institutional adoption of blockchain technology and could lead to the widespread use of tokenized financial instruments globally.