













Ethereum Security Settlement Repricing: Beyond the Rollup Narrative

Ethereum security settlement

COIN4U IN YOUR SOCIAL FEED

Learn Ethereum security settlement repricing: why markets shift from rollup hype to settlement value, what it means for ETH demand, fees, and adoption. For years, the dominant storyline around Ethereum’s scaling roadmap has been rollup-centric. If you followed crypto research, you likely heard the same refrain: rollups will handle execution, Ethereum will provide data availability and security, and the base layer will become the backbone that anchors an expanding universe of Layer 2 networks. That story wasn’t wrong, but it was incomplete—and markets tend to reprice incomplete stories when the real value proposition becomes clearer. This is where Ethereum security settlement enters the conversation as a powerful lens for understanding why Ethereum may be repriced, not simply as a “rollup hub,” but as a security settlement layer that underwrites trust at internet scale.

Repricing is a market process, not a marketing slogan. It happens when participants update what they believe they are buying. In a rollup-centric phase, many investors primarily valued Ethereum through the lens of throughput, fees, and scaling capacity: how many transactions can Ethereum “handle,” and how cheaply can users transact? But a settlement-centric phase reframes the value question. Instead of focusing on raw execution volume, it emphasizes what Ethereum uniquely sells to the world: credible neutrality, resilient finality, censorship resistance, economic security, and a globally verifiable ledger that others can safely build on. In other words, Ethereum security settlement becomes the product, and execution becomes modular.

Why Ethereum’s Narrative Is Shifting—and Why Markets Care

This shift matters because narratives influence capital allocation. A rollup-centric mindset can produce confusion when fees compress on the base layer or when activity migrates to Layer 2. Critics may conclude Ethereum is “losing revenue” or “outsourcing demand.” A settlement-layer mindset sees the same development differently: the network is scaling by specializing. Ethereum becomes the platform that guarantees security and settlement, while rollups compete in execution, UX, and app-specific customization. Under this model, Ethereum’s value is tied to how much economic activity depends on its security guarantees—how many assets, rollups, institutions, and protocols choose Ethereum as their final arbiter of truth.

In this article, we’ll explain the Ethereum security settlement repricing thesis in detail, clarify what “security settlement layer” means, explore how a rollup-centric worldview differs from a settlement-centric one, and examine the practical implications for ETH demand, fees, staking, and long-term adoption. You’ll also see relevant LSI keywords such as Ethereum settlement layer, rollup-centric scaling, Layer 2 ecosystems, modular blockchain, and Ethereum economic security, integrated naturally to support search visibility.

What “Ethereum Repricing” Means in Plain Terms

Repricing is the market’s way of correcting expectations. When investors misunderstand how value flows through a network, they may overemphasize the wrong metrics. The result is mispricing—either pessimism during transitions or exuberance during hype cycles. The Ethereum security settlement thesis argues that Ethereum’s core value is increasingly understood as security and final settlement, rather than being judged primarily as the place where every transaction is executed.

Rollup-Centric Value: The Old Default

In a rollup-centric framing, Ethereum’s success is often measured by base-layer throughput, transaction counts, and fee revenue directly on L1. This mindset implicitly assumes the “best blockchain” is the one that processes the most activity natively. When rollups reduce L1 execution load, the rollup-centric framing can interpret that as a weakening of Ethereum’s role.

Settlement-Centric Value: The Emerging Lens

In the settlement-centric framing, Ethereum’s success is measured by how much value relies on its security. Even if execution moves off-chain or to Layer 2, Ethereum still benefits if rollups publish data, settle disputes, finalize states, and secure assets via Ethereum’s consensus and economic guarantees. Under this view, Ethereum security settlement becomes more like a global trust engine than a simple transaction processor.

From Rollup-Centric to Security Settlement Layer: What Actually Changes?

Ethereum didn’t suddenly “become” a settlement layer—it always was. What changes is what the market chooses to emphasize. The transition toward Ethereum security settlement repricing becomes obvious when you look at Ethereum’s modular approach: separate execution from settlement, and let specialized layers do what they do best.

Execution Moves, Settlement Stays

Rollups execute transactions elsewhere, then post proofs and/or data back to Ethereum. This means users get cheaper transactions and better UX while still inheriting Ethereum’s security properties—assuming the rollup is designed properly. The settlement guarantee remains anchored to Ethereum, which is precisely why Ethereum security settlement matters more than raw L1 transaction counts.

Security as a Service

A helpful way to understand this shift is to think of Ethereum as “security as a service.” Rollups, token issuers, and even institutions can purchase Ethereum-grade security by aligning their final settlement to Ethereum. When more systems rely on Ethereum’s security and finality, demand for Ethereum blockspace (for data, proofs, and settlement) becomes more structural and less dependent on end-user transaction counts on L1.

Why Rollups Don’t “Steal” Ethereum Value—They Re-route It

A common confusion is that rollups reduce L1 fees, so they must reduce Ethereum’s value. That argument assumes Ethereum’s only product is expensive execution. The Ethereum security settlement thesis flips that assumption: rollups expand the total market that Ethereum can secure, and they create a broader surface area of dependence on Ethereum finality.

Rollups Expand Adoption Without Breaking the Base Layer

Cheaper transactions bring in more users and more applications. While much of that execution happens on L2, the integrity of the system still depends on L1 settlement. The larger the rollup ecosystem becomes, the more Ethereum’s settlement role becomes indispensable, reinforcing Ethereum security settlement value.

Settlement Demand Can Grow Even If L1 “User Transactions” Shrink

If a million users transact on L2, those actions can be compacted into fewer L1 interactions—yet the economic value secured may be higher than before. This is a key reason repricing happens: investors stop counting transactions and start measuring secured value, settlement dependence, and security budget strength. In settlement terms, Ethereum security settlement can become more valuable even with fewer visible L1 user transactions.

The New Valuation Drivers: What Markets May Focus On Next

If Ethereum is being repriced toward Ethereum security settlement, the metrics that matter begin to shift.

Economic Security and the Cost to Attack

A settlement layer’s core promise is that it’s extremely costly to rewrite history. Ethereum’s security is underwritten by a large validator set and staked ETH. As the network’s security budget grows, Ethereum becomes a more attractive final settlement choice. Under the Ethereum security settlement lens, the cost to attack and the credibility of finality are central.

Blockspace as a Scarce Resource

Even in a rollup-heavy world, Ethereum blockspace remains scarce. Rollups compete for data availability, settlement, and proof verification. If demand for these services rises, Ethereum blockspace can remain valuable in a different form than simple retail transactions. The repricing argument is that Ethereum security settlement demand is more structural and institution-friendly.

Settlement Premium and Credible Neutrality

Settlement layers win when neutral parties trust them. Ethereum’s credible neutrality—its resistance to capture by a single actor—is part of why protocols and institutions can rely on it. This “settlement premium” can become a valuation pillar as more real-world value is tokenized and needs a neutral base.

How This Repricing Impacts ETH Demand

A settlement narrative should eventually translate into ETH demand mechanisms. Otherwise it’s just theory. The Ethereum security settlement view suggests several pathways through which ETH remains relevant.

ETH as Security Collateral

Staked ETH is the economic backbone of Ethereum’s settlement assurances. If more systems depend on Ethereum finality, the network’s economic security becomes more important. That can support long-term ETH demand as a security collateral asset.

ETH as the Fee Asset

Even if users transact on L2, many settlement-related interactions ultimately require fees on Ethereum. Rollups pay to publish data and settle state. As rollups scale, this can create baseline demand for Ethereum blockspace and, indirectly, ETH usage—supporting the Ethereum security settlement thesis.

ETH as the Coordination Asset Across Layers

In a multi-layer ecosystem, ETH can serve as a coordinating asset: collateral, liquidity, and settlement alignment across Layer 1 and Layer 2. This coordination role becomes more relevant as the ecosystem expands and becomes more modular.

Rollup-Centric Risks and Settlement-Layer Risks: What Could Undermine the Thesis?

A strong SEO article should also cover risks clearly. Ethereum security settlement repricing is a thesis, not a guarantee.

Risk 1: Rollup Fragmentation and Poor UX

If the user experience across rollups becomes too fragmented—too many bridges, too many fee tokens, too much complexity—adoption may slow. Ethereum can still be a settlement layer, but the ecosystem might struggle to deliver consumer-grade simplicity, weakening the broader growth narrative around Ethereum security settlement.

Risk 2: Alternative Settlement Layers Compete

Other networks can position themselves as settlement layers too. Ethereum’s advantage is security, neutrality, and ecosystem depth, but competition can pressure settlement premiums. The repricing thesis assumes Ethereum remains the most trusted settlement choice for high-value activity.

Risk 3: Fee Compression Without Compensating Demand

If settlement demand does not grow fast enough, and fee markets stay weak, critics may argue Ethereum isn’t capturing value. The settlement-layer view counters that security dependence matters more than short-term fees, but markets can be impatient. This tension is part of why Ethereum security settlement repricing can be volatile.

What This Means for Builders, Investors, and the Broader Ecosystem

The repricing story changes incentives and narratives for different groups.

For Builders: Design for Settlement, Not Just Speed

Builders may prioritize interoperability, proof systems, and safe settlement paths. If Ethereum is the anchor, rollups and apps must design with security inheritance in mind. The clearer Ethereum’s settlement role becomes, the more builders treat Ethereum security settlement as the default trust layer.

For Investors: Evaluate Secured Value, Not Just Transaction Counts

Investors often chase the most visible metric. A settlement thesis encourages deeper evaluation: how much value is secured, how sticky the ecosystem is, and how dependent rollups and tokenized assets are on Ethereum finality. Under this approach, Ethereum security settlement becomes an investment lens rather than a slogan.

For Institutions: A Neutral Final Ledger Is the Product

Institutions typically care about auditability, finality, and trust minimization. A security settlement layer is easier to justify than a consumer transaction chain. This is one reason the Ethereum security settlement narrative can become more dominant as tokenization and on-chain settlement mature.

Signs the Market Is Actually Repricing Ethereum

How can you tell this repricing is happening rather than just being talked about? Look for the narrative shifting in what people measure.

One sign is when analysis focuses less on “Ethereum TPS” and more on settlement dependence: rollup data posting, proof verification activity, growth in L2 ecosystems that still anchor to Ethereum, and increasing discussion of Ethereum’s security budget. Another sign is the tone of discourse: when observers stop saying “rollups are moving activity away from Ethereum” and start saying “rollups are scaling Ethereum’s settlement footprint,” the market is adopting the Ethereum security settlement framework.

Conclusion

Ethereum’s rollup-centric roadmap didn’t diminish Ethereum—it clarified Ethereum. As execution becomes modular and abundant, the most valuable layer becomes the one that guarantees truth. That is the heart of Ethereum security settlement repricing: Ethereum is increasingly valued not as a chain that must do everything, but as the security settlement layer that other systems depend on for finality, neutrality, and economic protection.

If this thesis continues to gain traction, it can reshape how investors judge Ethereum’s success, how builders design applications, and how institutions evaluate on-chain settlement. The rollup era is not a detour; it is the path that makes Ethereum’s settlement role bigger, not smaller. Over time, that shift can drive a repricing that reflects what Ethereum uniquely offers: the strongest shared foundation for securing value on the internet.

FAQs

Q: What does Ethereum security settlement mean in simple terms?

Ethereum security settlement means Ethereum’s main job is to provide strong finality and security guarantees for assets and networks, even if transactions are executed on rollups or other layers.

Q: Why is the market shifting from rollup-centric to settlement-centric thinking?

Because execution is becoming modular and cheaper on Layer 2, while secure final settlement remains scarce and valuable. The settlement layer is what guarantees trust when many systems interact.

Q: Do rollups reduce Ethereum’s value by moving transactions off L1?

Not necessarily. Rollups can expand adoption while still relying on Ethereum for settlement and security. Under the Ethereum security settlement view, that dependence can increase Ethereum’s long-term importance.

Q: What metrics matter most in a security settlement layer model?

Investors often focus on economic security, settlement activity, demand for blockspace related to data and proofs, and how much value depends on Ethereum finality rather than just raw transaction counts.

Q: What could weaken the Ethereum security settlement repricing thesis?

Major risks include poor rollup user experience, strong competition from alternative settlement networks, or settlement demand not growing enough to support the security budget and value capture long term.

Explore more articles like this

Subscribe to the Finance Redefined newsletter

A weekly toolkit that breaks down the latest DeFi developments, offers sharp analysis, and uncovers new financial opportunities to help you make smart decisions with confidence. Delivered every Friday

By subscribing, you agree to our Terms of Services and Privacy Policy

READ MORE

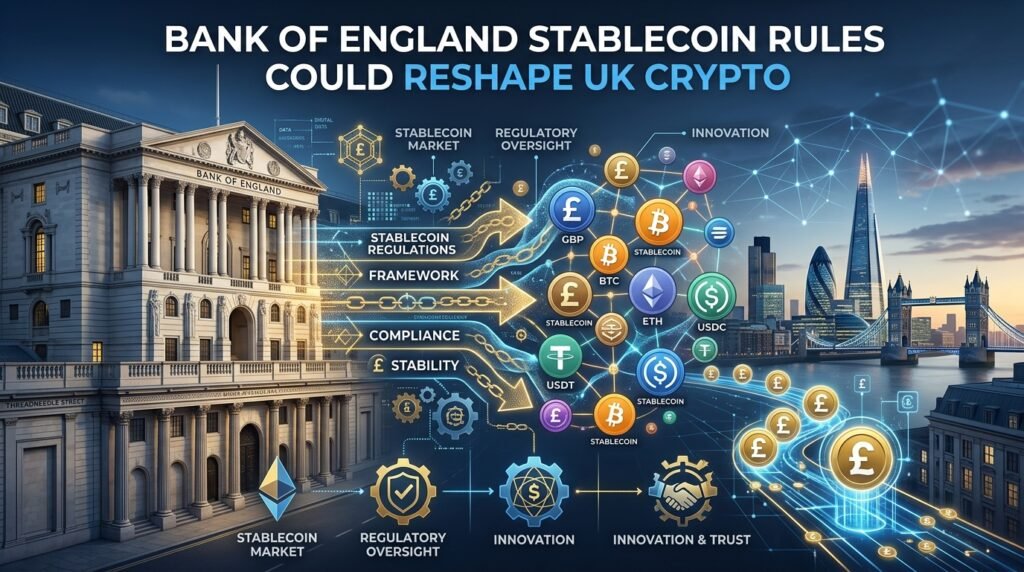
Bank of England Stablecoin Rules Could Reshape UK Crypto

COIN4U IN YOUR SOCIAL FEED

The global cryptocurrency industry is entering a new phase where regulation is no longer viewed solely as a barrier but increasingly as a framework for legitimacy and long-term growth. In the United Kingdom, this shift has become particularly noticeable as the Bank of England evaluates softer regulatory measures for UK stablecoin issuers. The move could significantly influence the future of digital payments, blockchain innovation, and the broader crypto economy across Europe.

Stablecoins have become one of the most important components of the digital asset ecosystem. Unlike highly volatile cryptocurrencies such as Bitcoin or Ethereum, stablecoins are designed to maintain a fixed value, usually pegged to traditional fiat currencies like the British pound or the US dollar. Because of this stability, they are increasingly used for payments, remittances, decentralized finance applications, and cross-border transactions.

The possibility that the Bank of England may adopt more flexible rules for stablecoin issuers has sparked considerable debate among policymakers, crypto businesses, investors, and financial institutions. Supporters argue that softer regulations could encourage innovation, attract blockchain companies to the UK, and strengthen London’s position as a global fintech hub. Critics, however, remain concerned about financial stability risks, consumer protection, and the potential impact on the traditional banking system.

As regulators worldwide attempt to balance innovation with oversight, the UK’s approach toward stablecoins may become a model for other jurisdictions. Understanding why the Bank of England is reconsidering its stance, what the proposed changes could mean, and how they may affect the broader crypto industry is essential for anyone following the evolution of digital finance.

Understanding Stablecoins and Their Growing Importance

Stablecoins occupy a unique position in the cryptocurrency market because they bridge the gap between traditional finance and decentralized digital assets. While cryptocurrencies like Bitcoin experience dramatic price swings, stablecoins aim to provide predictable value by backing their tokens with reserves such as cash, government bonds, or other liquid assets.

The importance of stablecoins has grown rapidly over the past few years. Traders use them to move funds between exchanges without converting back into fiat currency. Businesses use them for faster international transactions, while decentralized finance platforms rely heavily on stablecoin liquidity for lending, borrowing, and yield-generating activities.

The global stablecoin market has expanded into hundreds of billions of dollars in circulation, demonstrating how central these assets have become to the digital economy. This rapid growth has naturally attracted the attention of regulators, including the Bank of England, which sees both opportunities and risks in the widespread adoption of digital payment systems.

For the UK, stablecoins represent more than just another crypto trend. They are increasingly viewed as part of the future infrastructure of payments and financial technology. If properly regulated, stablecoins could improve transaction efficiency, reduce payment costs, and encourage innovation in digital commerce.

Why the Bank of England Is Reconsidering Stablecoin Rules

The Bank of England has traditionally taken a cautious approach toward cryptocurrencies and digital assets. Financial regulators have often warned about volatility, money laundering risks, and threats to financial stability. However, attitudes are beginning to evolve as blockchain technology matures and institutional interest grows.

One major reason for reconsidering stablecoin regulations is competition. Countries around the world are racing to become leaders in digital finance. The European Union has introduced the Markets in Crypto-Assets framework, while the United States continues to debate federal stablecoin legislation. If the UK adopts excessively strict rules, crypto businesses could simply relocate to more favorable jurisdictions.

Another important factor is innovation within the UK financial sector. London has long been regarded as one of the world’s leading financial centers. Policymakers increasingly recognize that maintaining this status requires embracing emerging technologies rather than resisting them. Softer rules for stablecoin issuers may encourage startups, blockchain firms, and fintech companies to establish operations in the UK.

The Bank of England also understands that stablecoins are likely to play a larger role in the future of payments. Consumers and businesses are demanding faster, cheaper, and more efficient digital transaction systems. A carefully managed stablecoin market could help modernize payment infrastructure while supporting economic competitiveness.

Potential Changes to UK Stablecoin Regulations

Although specific details continue to emerge, discussions around softer stablecoin rules suggest that regulators may ease some of the more restrictive requirements previously considered for issuers. Earlier proposals included stringent reserve management standards, capital requirements, and banking-style supervision that many crypto firms believed would be too burdensome.

Under a more flexible framework, stablecoin issuers could receive regulatory treatment that better reflects the unique nature of digital asset businesses rather than forcing them into traditional banking categories. This distinction is critical because many blockchain companies argue that applying conventional banking rules to stablecoins may stifle innovation and limit growth.

The Bank of England may also consider allowing issuers greater flexibility regarding reserve composition. Instead of requiring all reserves to be held exclusively in central bank deposits, issuers might be permitted to hold highly liquid assets such as government securities. Such changes could make stablecoin operations more economically viable.

Regulators are also examining proportional oversight models. Smaller issuers may face lighter compliance obligations compared to larger firms whose stablecoins could pose systemic financial risks. This tiered approach would allow innovation to flourish while ensuring that major players remain subject to appropriate safeguards.

The Impact on the UK Crypto Industry

A softer regulatory environment could have transformative effects on the UK crypto sector. Many blockchain companies have expressed frustration over regulatory uncertainty, which has made it difficult to scale operations or attract institutional investment. More balanced stablecoin rules may restore confidence among entrepreneurs and investors alike.

The UK could become a preferred destination for crypto startups seeking regulatory clarity combined with access to one of the world’s largest financial ecosystems. This could result in increased venture capital investment, job creation, and technological innovation across the fintech sector.

For institutional investors, clearer stablecoin regulations may also reduce perceived risks associated with digital assets. Banks, payment processors, and large corporations are more likely to engage with blockchain technology when they operate within a recognized legal framework.

The broader financial services industry may also benefit. Stablecoins can improve cross-border settlements, reduce transaction times, and lower operational costs for businesses handling international payments. These advantages could strengthen the UK’s position in global finance while supporting economic modernization.

How Softer Stablecoin Rules Could Influence Consumers
Bank of England Stablecoin Rules Could Reshape UK Crypto

Consumers may experience several benefits if stablecoin regulations become more innovation-friendly. One of the most significant advantages is faster and cheaper digital payments. Traditional international bank transfers can take days and involve substantial fees, whereas stablecoin transactions can often settle within minutes.

Digital wallets integrated with regulated stablecoins could also increase financial accessibility. Individuals without full access to traditional banking services may find it easier to participate in digital commerce through blockchain-based payment systems.

Additionally, competition within the payments sector could encourage innovation in user experience, security, and transaction efficiency. As more companies enter the stablecoin market, consumers may gain access to a broader range of financial products and services.

However, regulators must still ensure adequate consumer protection. Stablecoin users need confidence that their assets are properly backed and redeemable. Transparent reserve reporting and operational safeguards remain essential components of any successful regulatory framework.

Financial Stability Concerns Remain Central

Despite growing optimism around stablecoins, the Bank of England continues to emphasize financial stability risks. Stablecoins that become widely adopted could eventually influence monetary policy, banking liquidity, and payment systems at a national scale.

One major concern involves the possibility of rapid redemption events, sometimes described as digital bank runs. If users lose confidence in a stablecoin issuer, mass withdrawals could create liquidity pressures that spread through the broader financial system.

There are also concerns regarding interconnectedness between traditional finance and crypto markets. As banks and financial institutions increase exposure to digital assets, instability in one sector could potentially affect the other.

The Bank of England therefore faces the difficult task of balancing innovation with risk management. Softer rules do not necessarily mean the absence of regulation. Instead, policymakers appear to be exploring frameworks that encourage growth while maintaining safeguards against systemic threats.

The Global Stablecoin Regulatory Landscape

The UK’s evolving stance on stablecoins reflects broader global trends. Governments and central banks worldwide are actively developing digital asset policies to address the rapid expansion of blockchain technology.

In the European Union, regulators have implemented the Markets in Crypto-Assets regulation, commonly known as MiCA. This framework establishes licensing requirements, reserve standards, and consumer protection rules for stablecoin issuers operating within EU member states.

In the United States, stablecoin legislation remains under debate, with lawmakers discussing reserve requirements, federal oversight, and the role of banking institutions in digital asset issuance. Regulatory uncertainty has created challenges for crypto companies attempting to operate nationwide.

Asian financial hubs such as Singapore and Hong Kong are also competing to attract blockchain businesses through clearer regulatory frameworks. These jurisdictions aim to position themselves as centers for digital asset innovation while maintaining oversight standards.

Against this backdrop, the UK’s approach carries substantial importance. A balanced regulatory strategy could help the country compete internationally while shaping future standards for stablecoin governance.

Stablecoins and the Future of Digital Payments

The debate surrounding stablecoin regulation extends beyond cryptocurrency markets. Many experts believe stablecoins could fundamentally transform how money moves across the global economy.

Traditional payment systems often rely on intermediaries that increase transaction costs and processing times. Stablecoins, powered by blockchain networks, offer near-instant settlement capabilities that can significantly improve efficiency.

Large corporations are already exploring stablecoin integrations for commerce, payroll systems, and cross-border transactions. Financial institutions are likewise examining how blockchain-based settlement systems could reduce operational friction.

The Bank of England recognizes that digital payments are evolving rapidly. By creating a regulatory environment that supports responsible innovation, the UK could play a major role in shaping the future financial infrastructure of the digital economy.

The Relationship Between Stablecoins and Central Bank Digital Currencies

Another important aspect of the discussion involves the relationship between stablecoins and central bank digital currencies, often called CBDCs. Many central banks, including the Bank of England, are researching or developing state-backed digital currencies.

Unlike private stablecoins, CBDCs are issued directly by central banks and represent sovereign digital money. Some policymakers initially viewed CBDCs as competitors to private stablecoins, but attitudes are becoming more nuanced.

There is growing recognition that both systems may coexist. Stablecoins can drive private-sector innovation and specialized financial applications, while CBDCs may provide government-backed digital payment infrastructure.

The Bank of England’s softer stance toward stablecoin issuers could indicate a willingness to encourage a hybrid digital finance ecosystem where regulated private innovation complements public monetary systems.

Challenges Stablecoin Issuers Still Face

Even if regulations become more flexible, stablecoin issuers will continue to face significant operational and compliance challenges. Transparency remains one of the industry’s biggest issues. Regulators and consumers alike demand reliable proof that reserves fully back issued tokens.

Cybersecurity is another major concern. Stablecoin platforms must protect user funds and transaction systems from hacking attempts, fraud, and technical failures. As adoption grows, these risks become increasingly significant.

Issuers must also navigate evolving international regulations. Because blockchain networks operate globally, companies often face overlapping compliance obligations across multiple jurisdictions.

Reputation and trust will ultimately determine long-term success. Stablecoin issuers that prioritize transparency, security, and regulatory cooperation are more likely to gain mainstream adoption and institutional support.

What This Means for Investors and Crypto Markets

The possibility of softer UK stablecoin rules has generated considerable attention among crypto investors. Regulatory clarity often serves as a bullish signal for digital asset markets because it reduces uncertainty surrounding future business operations.

A supportive environment for stablecoins may increase liquidity throughout the crypto ecosystem. Stablecoins play a critical role in trading, lending, and decentralized finance applications. Easier access to regulated stablecoin services could encourage broader participation in digital asset markets.

Institutional investors may also become more comfortable entering the sector. Pension funds, asset managers, and financial institutions typically require clear compliance standards before engaging with emerging technologies.

At the same time, investors should remain aware of ongoing risks. Regulatory developments can change rapidly, and stablecoin markets remain vulnerable to technological, operational, and economic pressures.

Conclusion

The Bank of England’s consideration of softer rules for UK stablecoin issuers marks an important moment in the evolution of digital finance. Rather than viewing cryptocurrencies solely as speculative assets, regulators increasingly recognize the potential of stablecoins to modernize payment systems, encourage fintech innovation, and strengthen the UK’s position as a global financial leader.

Balancing innovation with financial stability will remain a delicate challenge. Regulators must create frameworks that protect consumers and the broader economy without discouraging technological progress. If successful, the UK could establish itself as one of the world’s most attractive destinations for blockchain businesses and digital asset innovation.

Stablecoins are no longer a niche component of the crypto market. They are becoming a central part of the future financial ecosystem. The decisions made by the Bank of England today may therefore shape not only the UK’s digital economy but also the broader global approach to cryptocurrency regulation in the years ahead.

Explore more articles like this

Subscribe to the Finance Redefined newsletter

A weekly toolkit that breaks down the latest DeFi developments, offers sharp analysis, and uncovers new financial opportunities to help you make smart decisions with confidence. Delivered every Friday

By subscribing, you agree to our Terms of Services and Privacy Policy

READ MORE

ADD PLACEHOLDER