














Institutional Money Is Coming to Bitcoin—Slowly

Institutional Money Is Coming to Bitcoin

COIN4U IN YOUR SOCIAL FEED

The narrative surrounding Bitcoin has shifted dramatically over the past few years. Once dismissed as a speculative digital experiment, it is now increasingly viewed as a legitimate asset class attracting serious attention from global financial institutions. Headlines frequently highlight billions flowing into crypto markets, spot Bitcoin ETFs, and corporate treasuries adding Bitcoin to their balance sheets. However, despite the hype, the reality of institutional adoption is far more nuanced—and significantly slower—than many investors anticipate.

According to Adam Back, a prominent figure in the crypto ecosystem and CEO of Blockstream, institutional money is indeed coming for Bitcoin—but not at the pace many expect. His recent remarks emphasize a critical truth: large-scale capital does not move overnight.

This article explores why institutional money in Bitcoin is progressing slowly, what factors influence this adoption curve, and what it means for the future of the cryptocurrency market.

The Rise of Institutional Interest in Bitcoin

From Retail Speculation to Institutional Asset

Bitcoin’s early growth was largely driven by retail investors and tech enthusiasts. Over time, however, its narrative evolved into that of “digital gold”, a hedge against inflation and monetary instability. This transformation attracted institutional players such as hedge funds, asset managers, and even pension funds.

The introduction of Bitcoin ETFs marked a turning point. These financial instruments provide traditional investors with exposure to Bitcoin without directly holding the asset, lowering entry barriers and increasing accessibility.

The Role of Major Financial Institutions

Global financial giants like BlackRock and Morgan Stanley have entered the crypto space, signaling growing confidence. Their involvement has fueled expectations of a massive influx of institutional capital.

Yet, despite these developments, actual allocation levels remain modest. Many institutions are still in the exploration and risk-assessment phase, rather than full-scale adoption.

Adam Back’s Perspective: Why Adoption Is Slower Than Expected

Institutional Money Takes Time to Deploy

Adam Back highlights a key misconception: people often assume that once institutions show interest, capital will flood the market instantly. In reality, institutional investment cycles are slow, deliberate, and heavily regulated.

He notes that even though ETFs are available, fund managers have not yet fully implemented recommended allocations—often around 2% to 4% of portfolios.

This delay is not due to lack of interest but rather the complexity of institutional decision-making processes.

A 12–18 Month Timeline for Capital Flows

Back suggests that meaningful institutional inflows could take 12 to 18 months to materialize.

This timeline reflects the reality of how large organizations operate. Investment committees, compliance checks, and risk models must all align before capital is deployed.

Key Factors Slowing Institutional Bitcoin Adoption

Regulatory Uncertainty

One of the biggest barriers to institutional investment is unclear regulatory frameworks. Institutions require legal clarity before allocating significant capital to any asset class.

While progress is being made globally, regulatory inconsistencies still create hesitation among major investors.

Risk Management and Volatility

Bitcoin’s volatility remains a concern. Institutional investors prioritize risk-adjusted returns, and the crypto market’s price swings can be difficult to integrate into traditional portfolios.

Even with ETFs, volatility management strategies must be carefully developed before large-scale investment.

Infrastructure and Custody Solutions

Although the crypto ecosystem has matured, institutions still require secure custody solutions, compliance tools, and reliable trading infrastructure.

Companies like Coinbase and Fidelity Investments have made progress in this area, but adoption takes time.

Internal Decision-Making Processes

Institutional investment decisions involve multiple layers of approval. Unlike retail investors, institutions must navigate:

  • Investment committees
  • Risk assessments
  • Compliance checks
  • Strategic alignment

This inherently slows down capital deployment.

The Impact of Bitcoin ETFs on Institutional Adoption
Impact of Bitcoin ETFs on Institutional Adoption

A Gateway for Traditional Investors

Bitcoin ETFs are widely seen as a bridge between traditional finance and crypto markets. They allow institutions to gain exposure without dealing with private keys or blockchain complexities.

Back considers ETFs one of the most significant developments in Bitcoin’s history, even more impactful than favorable government policies.

Why ETFs Haven’t Triggered Immediate Inflows

Despite their importance, ETFs have not yet led to massive institutional inflows. This is because:

  • Institutions are still evaluating performance
  • Portfolio allocations are being tested gradually
  • Market conditions influence timing

In other words, ETFs are a long-term catalyst, not a short-term trigger.

Structural Demand vs. Speculative Hype

A Shift in Market Dynamics

Adam Back emphasizes that Bitcoin’s next major growth phase will be driven by structural demand, not retail speculation.

This marks a significant shift in how the market operates. Instead of rapid price spikes fueled by hype, future growth may be:

  • Slower
  • More stable
  • Fundamentally driven

Institutional Capital Pipelines

Institutional adoption involves capital pipelines that develop over time. These include:

  • ETF inflows
  • Corporate treasury allocations
  • Long-term investment strategies

Such pipelines create sustained demand rather than short-term volatility.

The Role of Macro Economics in Institutional Bitcoin Investment

Interest Rates and Liquidity

Macroeconomic conditions play a crucial role in determining when institutions allocate capital to Bitcoin. Factors such as interest rates, inflation, and liquidity directly impact investment decisions.

For example, lower interest rates often encourage risk-taking, making Bitcoin more attractive.

Global Financial Uncertainty

Bitcoin’s appeal as a hedge against economic instability continues to attract attention. However, institutions typically wait for clear macro signals before making significant moves.

Institutional vs. Retail Investors: A Fundamental Difference

Speed vs. Scale

Retail investors can act quickly, often driven by market sentiment. Institutional investors, on the other hand, move slowly but deploy massive amounts of capital.

This creates a dynamic where:

  • Retail drives short-term price movements
  • Institutions shape long-term trends

Long-Term Investment Horizons

Institutions typically invest with multi-year horizons, focusing on sustainable growth rather than quick gains.

This aligns with Back’s view that Bitcoin’s future growth will be gradual and structural.

What This Means for Bitcoin’s Future

Gradual Price Appreciation

If institutional adoption continues at a steady pace, Bitcoin’s price is likely to experience gradual upward movement rather than explosive rallies.

Increased Market Stability

As institutions enter the market, Bitcoin could become less volatile, making it more attractive to conservative investors.

A Maturing Asset Class

Institutional involvement signals Bitcoin’s transition into a mature financial asset, comparable to gold or equities.

The Long-Term Outlook: Patience Is Key

Adam Back’s insights highlight an important lesson for investors: patience is essential. While institutional money is indeed coming, it will not arrive overnight.

Instead, the market is undergoing a slow but steady transformation, laying the groundwork for long-term growth.

Conclusion

The idea that institutional money is flooding into Bitcoin overnight is a misconception. As explained by Adam Back, the reality is far more gradual. Institutional adoption involves complex processes, regulatory considerations, and long-term strategies that naturally slow down capital deployment.

However, this slower pace should not be seen as a negative. On the contrary, it indicates a more sustainable and stable future for Bitcoin. As institutional infrastructure strengthens and confidence grows, Bitcoin is poised to evolve into a cornerstone of the global financial system.

For investors, the key takeaway is clear: the future of Bitcoin is not about rapid gains but steady, structural growth driven by institutional adoption.

Explore more articles like this

Subscribe to the Finance Redefined newsletter

A weekly toolkit that breaks down the latest DeFi developments, offers sharp analysis, and uncovers new financial opportunities to help you make smart decisions with confidence. Delivered every Friday

By subscribing, you agree to our Terms of Services and Privacy Policy

READ MORE

Cryptocurrency and Digital Commerce Regulation Guide

Cryptocurrency and Digital

COIN4U IN YOUR SOCIAL FEED

The rapid rise of cryptocurrency and the expansion of digital commerce have reshaped modern finance, online business models and global economic behaviour. What began as a technological experiment driven by decentralised digital currencies has evolved into a sophisticated ecosystem that includes blockchain networks, tokenised assets, decentralised finance and innovative digital payment solutions. As more consumers and businesses adopt these technologies, the need for strong and balanced cryptocurrency and digital commerce regulation becomes increasingly essential. Regulation must address transparency, safety, consumer protection and financial stability without hindering the innovation that fuels economic progress.

The regulatory environment around cryptocurrency and digital commerce is complex because it must align with rapidly evolving technologies. Governments across the world are trying to create frameworks that ensure security and accountability while supporting growth in financial and technological sectors. Businesses involved in digital trade must understand how regulations apply to them, and users must be aware of how these rules protect their rights and assets. This article explores the full landscape of cryptocurrency and digital commerce regulation, providing clarity on why regulation matters, how laws differ across regions and what the future of the digital economy might look like.

Cryptocurrency and Digital Commerce

To understand the purpose and structure of cryptocurrency and digital commerce regulation, it is important to first define the digital components at the heart of this transformation. Cryptocurrency refers to digital assets secured by cryptographic algorithms and powered by distributed ledger technology. These assets operate on blockchain networks, where transactions are recorded transparently and immutably. Bitcoin and Ethereum are the two most widely recognised cryptocurrencies, but thousands of tokens exist today, each serving different functions in digital ecosystems. Unlike traditional currencies, cryptocurrencies operate without a central authority, allowing fast, borderless and peer-to-peer transactions that bypass traditional banking systems.

Digital commerce refers to the buying and selling of goods and services using electronic platforms, ranging from online stores and mobile apps to digital marketplaces and subscription platforms. With the integration of cryptocurrencies into mainstream commerce, digital commerce has expanded into a broader digital economy. Users can purchase goods, access digital services or invest in tokenised assets directly from their digital wallets. This integration, while beneficial, introduces new regulatory challenges, especially in areas such as consumer rights, taxation, transaction transparency and platform accountability.

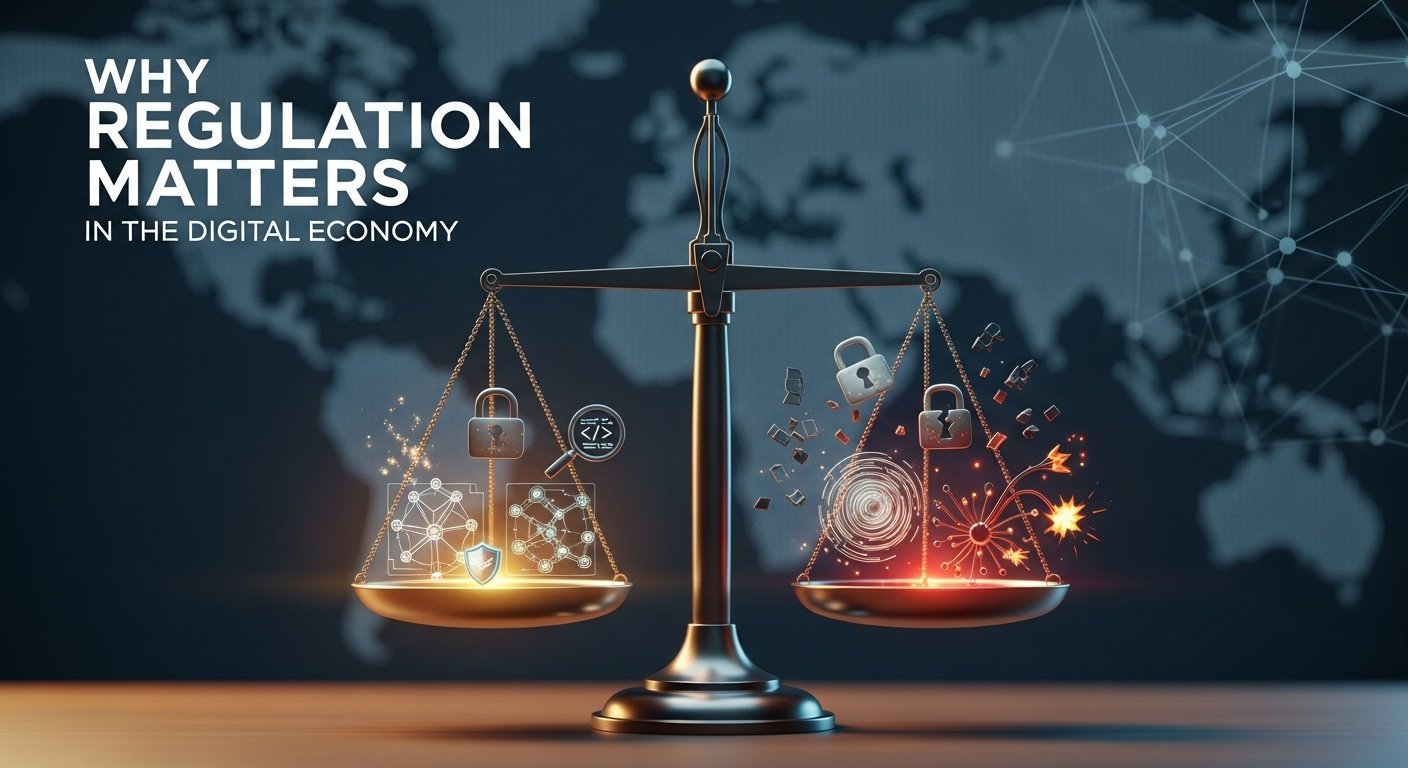
Why Regulation Matters in the Digital Economy

Why Regulation Matters in the Digital Economy

Regulation in the cryptocurrency and digital commerce space is necessary to ensure stability, prevent abuse and promote trust. Consumers engaging with cryptocurrencies often lack deep technical which can expose them to risks such as price volatility, phishing attacks, wallet compromises and fraudulent platforms. Without regulatory protection, users may suffer irreversible losses. Consumer protection laws adapted to digital technology ensure that businesses offering crypto services maintain transparent policies, secure infrastructure and fair dispute mechanisms.

Another major reason regulation is important is the need to combat financial crime. Cryptocurrencies have occasionally been misused for illegal activities because transactions can be pseudonymous and instantaneous. Regulators implement anti-money laundering controls and require service providers to verify user identities to reduce the potential for illicit activity. These rules allow law enforcement and financial authorities to detect suspicious behaviour while enabling legitimate transactions to flourish. By enforcing compliance, governments prevent crypto from becoming a haven for criminal enterprises.

Regulation also ensures fairness across the financial industry. Traditional finance institutions must comply with extensive legal requirements, while early crypto platforms once operated without comparable oversight. Creating a level regulatory framework ensures healthy competition while preventing new companies from gaining unfair advantages through regulatory gaps. In the long run, well-crafted regulations support innovation by creating clear rules, encouraging responsible growth and building confidence among investors, consumers and businesses.

Key Pillars of Cryptocurrency and Digital Commerce Regulation

Regulatory systems around the world generally focus on a few major themes, despite differences in legal traditions and economic priorities. One of the most important themes involves the classification of digital assets. Depending on their design and purpose, cryptocurrencies may be treated as currencies, commodities, securities or utility tokens. This classification determines which laws apply to the asset and how businesses must handle it. For example, a token that resembles an investment contract may be subject to securities regulation, requiring detailed disclosures and investor protections.

Another key pillar involves licensing and registration for crypto-related service providers. Exchanges, custodial wallet providers, payment processors and platforms offering token investment opportunities often need official authorisation to operate. Regulators require these businesses to maintain proper financial records, secure customer assets and demonstrate that they can operate safely. Licensing ensures that service providers meet minimum standards, reducing the risk of fraud or mismanagement.

Compliance with anti-money laundering and know-your-customer laws is another foundational aspect of cryptocurrency and digital commerce regulation. Businesses handling digital assets must verify customer identities, monitor unusual activities and report suspicious transactions to financial authorities. These procedures discourage criminal misuse of cryptocurrency and help integrate digital assets into the global financial system. Users may find identity verification burdensome, but it is essential for maintaining the integrity of the digital economy.

Taxation is another major element of regulation. Governments must determine how to tax crypto transactions, whether treating gains as capital income, business income or property-based gains. Merchants accepting cryptocurrency may need to convert values for tax reporting at the moment of the transaction. Staking rewards, mining profits and NFT sales may also carry tax obligations. Regulations help both individuals and businesses understand their responsibilities and avoid accidental non-compliance.

Finally, consumer rights and data protection form a growing area of digital commerce regulation. With users sharing personal information online and transacting digitally, rules surrounding privacy, cybersecurity, refund policies, and platform transparency are becoming increasingly important. Regulators expect businesses to secure sensitive information, communicate risks clearly and respond efficiently in case of breaches or service failures.

How Different Regions Approach Crypto and Digital Commerce

How Different Regions Approach Crypto and Digital Commerce

Regulatory approaches differ significantly across regions, reflecting varying attitudes toward innovation, financial stability and consumer protection. In North America, the regulatory environment is fragmented, especially in the United States, where different federal agencies interpret cryptocurrencies differently. Some agencies classify certain tokens as commodities while others treat them as securities. States may also impose individual licensing requirements, creating a multi-layered regulatory landscape. Canada has established a more streamlined system that treats many crypto trading platforms as securities dealers, requiring them to follow strict investor protection rules. Both countries pay close attention to issues related to stablecoins, decentralised platforms and tokenised securities.

Europe has moved toward a harmonised regulatory structure with the introduction of the Markets in Crypto-Assets framework. This regulation provides detailed rules for crypto asset service providers across the European Union, focusing on transparency, consumer protection and market integrity. Europe also applies strong privacy and e-commerce standards, which means crypto platforms must comply with multiple layers of regulation. As a region, the European Union leans toward treating digital assets similarly to traditional financial instruments while also supporting responsible innovation.

In the Asia-Pacific region, regulatory attitudes vary widely. Some countries promote technology development and crypto adoption by creating clear licensing regimes and innovation-friendly laws. Others impose strict limits on cryptocurrency trading or ban certain activities altogether. The region is diverse, but there is a common focus on controlling capital flows and ensuring financial stability. Many governments in the region pay special attention to cross-border payments, digital entertainment markets, gaming platforms and remittance services powered by blockchain.

Regulation of Crypto Payments in Digital Commerce

The use of cryptocurrency for everyday transactions has grown steadily, with more merchants accepting digital assets as payment for goods and services. Regulation plays a critical role in this area because both consumers and merchants need clarity on legal, tax and security aspects of crypto transactions. When a merchant receives cryptocurrency directly, they must understand how local laws treat digital assets, whether they must convert payments into fiat currency, and how to compute taxable income. Because crypto transactions are irreversible, consumer refund rights and chargeback policies must also be clearly defined.

Payment gateways that convert cryptocurrency to fiat currency offer additional convenience but also take on regulatory responsibilities. These companies often act as intermediaries and may need to comply with financial licensing rules, maintain secure processing systems and protect customer information. Their role makes cryptocurrency payments more accessible to merchants who prefer not to manage blockchain wallets themselves.

Stablecoins have become especially important in digital commerce because they offer the benefits of blockchain transactions without the extreme price volatility associated with many cryptocurrencies. However, stablecoins raise regulatory questions about issuer responsibility, reserve backing and systemic risk. Governments aim to ensure that stablecoin issuers hold sufficient assets to support redemption and operate with full transparency. As stablecoins become more integrated into digital commerce, they are likely to face increasingly detailed regulatory oversight.

See More: Comprehensive Guide to Cryptocurrency Blockchain and Digital Finance

Compliance Challenges for Businesses

Businesses operating in cryptocurrency and digital commerce face unique challenges because regulations evolve rapidly and differ across countries. One of the biggest challenges involves managing obligations across multiple jurisdictions. Since digital platforms typically serve global audiences, businesses may need to comply with several regulatory frameworks simultaneously. Some companies choose to limit services in certain regions to avoid legal complexity, while others invest heavily in compliance infrastructure to operate globally.

A second major challenge is balancing user privacy with regulatory oversight. Cryptocurrency users often prefer anonymity or pseudonymity, yet regulators require transparency for the sake of financial security and anti-crime measures. Businesses must find ways to respect user privacy while implementing identity verification and monitoring systems. Emerging technologies such as zero-knowledge proofs may eventually help reconcile privacy goals with regulatory requirements, but regulators are still learning how to apply these tools.

Cybersecurity presents another significant challenge. Digital assets are vulnerable to hacking, phishing attacks and technical failures. Businesses must implement strong security systems, conduct frequent audits and prepare detailed response plans for security incidents. Operational resilience is increasingly becoming a regulatory expectation, and companies that fail to secure customer assets may face penalties, reputational damage and loss of trust.

Future Trends in Cryptocurrency and Digital Commerce Regulation

The future of cryptocurrency and digital commerce regulation will likely involve greater integration between digital and traditional finance. As banks, fintech companies and established financial institutions adopt blockchain technology, regulatory frameworks may become more unified. Tokenisedd securities, digital bonds and central bank digital currencies are examples of products that will blur the line between decentralised and centralised finance. This convergence may lead to clearer rules and more predictable compliance expectations.

International cooperation is another emerging trend. Because blockchain networks operate globally, no single nation can regulate digital assets effectively on its own. International organisations and regulatory bodies are working toward consistent global standards on issues such as anti-money laundering, cross-border taxation and supervision of virtual asset service providers. More coordinated regulation can reduce fragmentation and help businesses operate more confidently across multiple markets.

Finally, regulation is becoming more technologically informed. Policymakers are increasingly willing to learn about blockchain mechanisms, smart contract design and decentralised architectures instead of applying outdated laws rigidly. This shift can encourage innovation by allowing regulators to craft rules that address outcomes rather than specific technologies. Regulatory sandboxes, pilot programs and public consultations will likely become more common as authorities seek to understand how emerging technologies can coexist with financial safeguards.

Conclusion

Cryptocurrency and digital commerce are transforming the global economy by enabling faster, more secure and more transparent ways of transferring value. As adoption grows, the importance of strong, clear and flexible cryptocurrency and digital commerce regulation becomes undeniable. Regulation protects consumers, prevents financial crime, maintains market integrity and creates a stable environment for innovation. While regulatory approaches differ across regions, the trend is toward more structured and cooperative frameworks that integrate digital assets into mainstream finance.

Users benefit when they understand how regulations affect their rights, security and responsibilities. Businesses succeed when they embrace compliance as part of their long-term strategy and design their platforms with regulatory expectations in mind. As the digital economy evolves, those who recognise regulation as. Pillar of trust—not a barrier—will be best positioned to thrive in the future of digital finance.

Explore more articles like this

Subscribe to the Finance Redefined newsletter

A weekly toolkit that breaks down the latest DeFi developments, offers sharp analysis, and uncovers new financial opportunities to help you make smart decisions with confidence. Delivered every Friday

By subscribing, you agree to our Terms of Services and Privacy Policy

READ MORE

ADD PLACEHOLDER