
























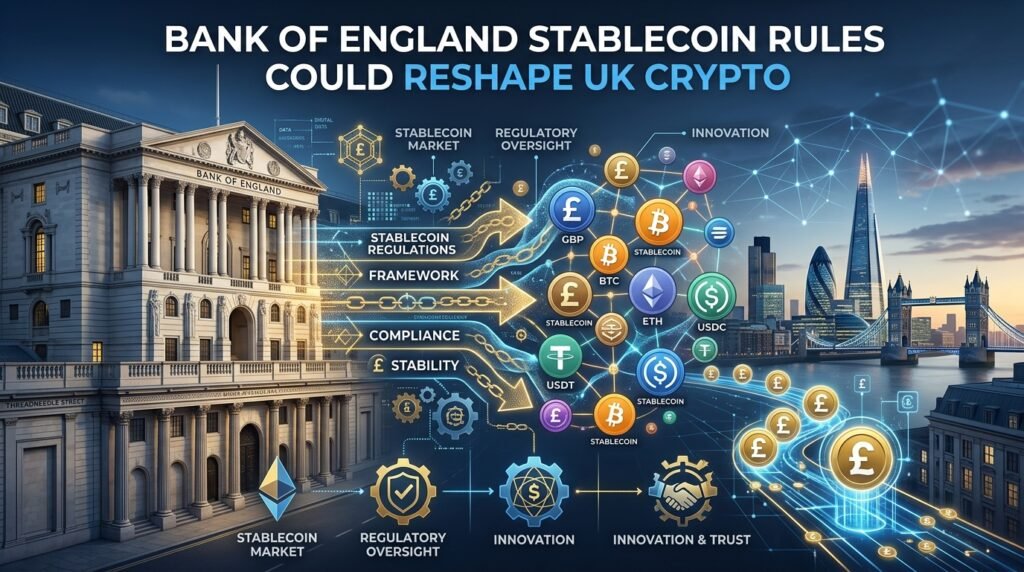
The global cryptocurrency industry is entering a new phase where regulation is no longer viewed solely as a barrier but increasingly as a framework for legitimacy and long-term growth. In the United Kingdom, this shift has become particularly noticeable as the Bank of England evaluates softer regulatory measures for UK stablecoin issuers. The move could significantly influence the future of digital payments, blockchain innovation, and the broader crypto economy across Europe.
Stablecoins have become one of the most important components of the digital asset ecosystem. Unlike highly volatile cryptocurrencies such as Bitcoin or Ethereum, stablecoins are designed to maintain a fixed value, usually pegged to traditional fiat currencies like the British pound or the US dollar. Because of this stability, they are increasingly used for payments, remittances, decentralized finance applications, and cross-border transactions.
The possibility that the Bank of England may adopt more flexible rules for stablecoin issuers has sparked considerable debate among policymakers, crypto businesses, investors, and financial institutions. Supporters argue that softer regulations could encourage innovation, attract blockchain companies to the UK, and strengthen London’s position as a global fintech hub. Critics, however, remain concerned about financial stability risks, consumer protection, and the potential impact on the traditional banking system.
As regulators worldwide attempt to balance innovation with oversight, the UK’s approach toward stablecoins may become a model for other jurisdictions. Understanding why the Bank of England is reconsidering its stance, what the proposed changes could mean, and how they may affect the broader crypto industry is essential for anyone following the evolution of digital finance.
Understanding Stablecoins and Their Growing Importance
Stablecoins occupy a unique position in the cryptocurrency market because they bridge the gap between traditional finance and decentralized digital assets. While cryptocurrencies like Bitcoin experience dramatic price swings, stablecoins aim to provide predictable value by backing their tokens with reserves such as cash, government bonds, or other liquid assets.
The importance of stablecoins has grown rapidly over the past few years. Traders use them to move funds between exchanges without converting back into fiat currency. Businesses use them for faster international transactions, while decentralized finance platforms rely heavily on stablecoin liquidity for lending, borrowing, and yield-generating activities.
The global stablecoin market has expanded into hundreds of billions of dollars in circulation, demonstrating how central these assets have become to the digital economy. This rapid growth has naturally attracted the attention of regulators, including the Bank of England, which sees both opportunities and risks in the widespread adoption of digital payment systems.
For the UK, stablecoins represent more than just another crypto trend. They are increasingly viewed as part of the future infrastructure of payments and financial technology. If properly regulated, stablecoins could improve transaction efficiency, reduce payment costs, and encourage innovation in digital commerce.
Why the Bank of England Is Reconsidering Stablecoin Rules
The Bank of England has traditionally taken a cautious approach toward cryptocurrencies and digital assets. Financial regulators have often warned about volatility, money laundering risks, and threats to financial stability. However, attitudes are beginning to evolve as blockchain technology matures and institutional interest grows.
One major reason for reconsidering stablecoin regulations is competition. Countries around the world are racing to become leaders in digital finance. The European Union has introduced the Markets in Crypto-Assets framework, while the United States continues to debate federal stablecoin legislation. If the UK adopts excessively strict rules, crypto businesses could simply relocate to more favorable jurisdictions.
Another important factor is innovation within the UK financial sector. London has long been regarded as one of the world’s leading financial centers. Policymakers increasingly recognize that maintaining this status requires embracing emerging technologies rather than resisting them. Softer rules for stablecoin issuers may encourage startups, blockchain firms, and fintech companies to establish operations in the UK.
The Bank of England also understands that stablecoins are likely to play a larger role in the future of payments. Consumers and businesses are demanding faster, cheaper, and more efficient digital transaction systems. A carefully managed stablecoin market could help modernize payment infrastructure while supporting economic competitiveness.
Potential Changes to UK Stablecoin Regulations
Although specific details continue to emerge, discussions around softer stablecoin rules suggest that regulators may ease some of the more restrictive requirements previously considered for issuers. Earlier proposals included stringent reserve management standards, capital requirements, and banking-style supervision that many crypto firms believed would be too burdensome.
Under a more flexible framework, stablecoin issuers could receive regulatory treatment that better reflects the unique nature of digital asset businesses rather than forcing them into traditional banking categories. This distinction is critical because many blockchain companies argue that applying conventional banking rules to stablecoins may stifle innovation and limit growth.
The Bank of England may also consider allowing issuers greater flexibility regarding reserve composition. Instead of requiring all reserves to be held exclusively in central bank deposits, issuers might be permitted to hold highly liquid assets such as government securities. Such changes could make stablecoin operations more economically viable.
Regulators are also examining proportional oversight models. Smaller issuers may face lighter compliance obligations compared to larger firms whose stablecoins could pose systemic financial risks. This tiered approach would allow innovation to flourish while ensuring that major players remain subject to appropriate safeguards.
The Impact on the UK Crypto Industry
A softer regulatory environment could have transformative effects on the UK crypto sector. Many blockchain companies have expressed frustration over regulatory uncertainty, which has made it difficult to scale operations or attract institutional investment. More balanced stablecoin rules may restore confidence among entrepreneurs and investors alike.
The UK could become a preferred destination for crypto startups seeking regulatory clarity combined with access to one of the world’s largest financial ecosystems. This could result in increased venture capital investment, job creation, and technological innovation across the fintech sector.
For institutional investors, clearer stablecoin regulations may also reduce perceived risks associated with digital assets. Banks, payment processors, and large corporations are more likely to engage with blockchain technology when they operate within a recognized legal framework.
The broader financial services industry may also benefit. Stablecoins can improve cross-border settlements, reduce transaction times, and lower operational costs for businesses handling international payments. These advantages could strengthen the UK’s position in global finance while supporting economic modernization.
How Softer Stablecoin Rules Could Influence Consumers
Consumers may experience several benefits if stablecoin regulations become more innovation-friendly. One of the most significant advantages is faster and cheaper digital payments. Traditional international bank transfers can take days and involve substantial fees, whereas stablecoin transactions can often settle within minutes.
Digital wallets integrated with regulated stablecoins could also increase financial accessibility. Individuals without full access to traditional banking services may find it easier to participate in digital commerce through blockchain-based payment systems.
Additionally, competition within the payments sector could encourage innovation in user experience, security, and transaction efficiency. As more companies enter the stablecoin market, consumers may gain access to a broader range of financial products and services.
However, regulators must still ensure adequate consumer protection. Stablecoin users need confidence that their assets are properly backed and redeemable. Transparent reserve reporting and operational safeguards remain essential components of any successful regulatory framework.
Financial Stability Concerns Remain Central
Despite growing optimism around stablecoins, the Bank of England continues to emphasize financial stability risks. Stablecoins that become widely adopted could eventually influence monetary policy, banking liquidity, and payment systems at a national scale.
One major concern involves the possibility of rapid redemption events, sometimes described as digital bank runs. If users lose confidence in a stablecoin issuer, mass withdrawals could create liquidity pressures that spread through the broader financial system.
There are also concerns regarding interconnectedness between traditional finance and crypto markets. As banks and financial institutions increase exposure to digital assets, instability in one sector could potentially affect the other.
The Bank of England therefore faces the difficult task of balancing innovation with risk management. Softer rules do not necessarily mean the absence of regulation. Instead, policymakers appear to be exploring frameworks that encourage growth while maintaining safeguards against systemic threats.
The Global Stablecoin Regulatory Landscape
The UK’s evolving stance on stablecoins reflects broader global trends. Governments and central banks worldwide are actively developing digital asset policies to address the rapid expansion of blockchain technology.
In the European Union, regulators have implemented the Markets in Crypto-Assets regulation, commonly known as MiCA. This framework establishes licensing requirements, reserve standards, and consumer protection rules for stablecoin issuers operating within EU member states.
In the United States, stablecoin legislation remains under debate, with lawmakers discussing reserve requirements, federal oversight, and the role of banking institutions in digital asset issuance. Regulatory uncertainty has created challenges for crypto companies attempting to operate nationwide.
Asian financial hubs such as Singapore and Hong Kong are also competing to attract blockchain businesses through clearer regulatory frameworks. These jurisdictions aim to position themselves as centers for digital asset innovation while maintaining oversight standards.
Against this backdrop, the UK’s approach carries substantial importance. A balanced regulatory strategy could help the country compete internationally while shaping future standards for stablecoin governance.
Stablecoins and the Future of Digital Payments
The debate surrounding stablecoin regulation extends beyond cryptocurrency markets. Many experts believe stablecoins could fundamentally transform how money moves across the global economy.
Traditional payment systems often rely on intermediaries that increase transaction costs and processing times. Stablecoins, powered by blockchain networks, offer near-instant settlement capabilities that can significantly improve efficiency.
Large corporations are already exploring stablecoin integrations for commerce, payroll systems, and cross-border transactions. Financial institutions are likewise examining how blockchain-based settlement systems could reduce operational friction.
The Bank of England recognizes that digital payments are evolving rapidly. By creating a regulatory environment that supports responsible innovation, the UK could play a major role in shaping the future financial infrastructure of the digital economy.
The Relationship Between Stablecoins and Central Bank Digital Currencies
Another important aspect of the discussion involves the relationship between stablecoins and central bank digital currencies, often called CBDCs. Many central banks, including the Bank of England, are researching or developing state-backed digital currencies.
Unlike private stablecoins, CBDCs are issued directly by central banks and represent sovereign digital money. Some policymakers initially viewed CBDCs as competitors to private stablecoins, but attitudes are becoming more nuanced.
There is growing recognition that both systems may coexist. Stablecoins can drive private-sector innovation and specialized financial applications, while CBDCs may provide government-backed digital payment infrastructure.
The Bank of England’s softer stance toward stablecoin issuers could indicate a willingness to encourage a hybrid digital finance ecosystem where regulated private innovation complements public monetary systems.
Challenges Stablecoin Issuers Still Face
Even if regulations become more flexible, stablecoin issuers will continue to face significant operational and compliance challenges. Transparency remains one of the industry’s biggest issues. Regulators and consumers alike demand reliable proof that reserves fully back issued tokens.
Cybersecurity is another major concern. Stablecoin platforms must protect user funds and transaction systems from hacking attempts, fraud, and technical failures. As adoption grows, these risks become increasingly significant.
Issuers must also navigate evolving international regulations. Because blockchain networks operate globally, companies often face overlapping compliance obligations across multiple jurisdictions.
Reputation and trust will ultimately determine long-term success. Stablecoin issuers that prioritize transparency, security, and regulatory cooperation are more likely to gain mainstream adoption and institutional support.
What This Means for Investors and Crypto Markets
The possibility of softer UK stablecoin rules has generated considerable attention among crypto investors. Regulatory clarity often serves as a bullish signal for digital asset markets because it reduces uncertainty surrounding future business operations.
A supportive environment for stablecoins may increase liquidity throughout the crypto ecosystem. Stablecoins play a critical role in trading, lending, and decentralized finance applications. Easier access to regulated stablecoin services could encourage broader participation in digital asset markets.
Institutional investors may also become more comfortable entering the sector. Pension funds, asset managers, and financial institutions typically require clear compliance standards before engaging with emerging technologies.
At the same time, investors should remain aware of ongoing risks. Regulatory developments can change rapidly, and stablecoin markets remain vulnerable to technological, operational, and economic pressures.
Conclusion
The Bank of England’s consideration of softer rules for UK stablecoin issuers marks an important moment in the evolution of digital finance. Rather than viewing cryptocurrencies solely as speculative assets, regulators increasingly recognize the potential of stablecoins to modernize payment systems, encourage fintech innovation, and strengthen the UK’s position as a global financial leader.
Balancing innovation with financial stability will remain a delicate challenge. Regulators must create frameworks that protect consumers and the broader economy without discouraging technological progress. If successful, the UK could establish itself as one of the world’s most attractive destinations for blockchain businesses and digital asset innovation.
Stablecoins are no longer a niche component of the crypto market. They are becoming a central part of the future financial ecosystem. The decisions made by the Bank of England today may therefore shape not only the UK’s digital economy but also the broader global approach to cryptocurrency regulation in the years ahead.